You’ve spent thousands building your 4WD into the touring rig you want. But if something goes wrong, is your insurance policy actually keeping up with your build?
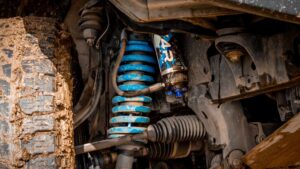
It’s surprisingly easy to underestimate just how much money is tied up in a modified 4WD. A bull bar here, a suspension upgrade there, then a winch, UHF, canopy, dual-battery setup, fridge, roof rack and a dozen smaller additions. Before long, you’ve added tens of thousands of dollars to the vehicle.
The problem is that your insurance policy might still reflect what your 4WD looked like years ago.
That’s why checking your insurance shouldn’t just be something you do when the renewal notice lands in your inbox. If you regularly modify your vehicle or use it for off-road touring, it’s worth reviewing exactly what’s covered, how much it’s covered for and, importantly, where that cover applies.
How much is your 4WD really worth?
The value of the vehicle itself is only part of the equation.
For many touring 4WDs, a significant chunk of their replacement cost is sitting in modifications and accessories. Think suspension, bar work, winches, canopies, electrical systems, auxiliary batteries, communications equipment, lighting and storage. And it’s often the less obvious stuff that gets forgotten.
An earlier version of this article used a modified Toyota HiLux as a case study. On paper, its owner thought he had done a pretty good job of accounting for everything fitted to it.
The original list included:
suspension lift
aftermarket wheels
catch can
bash plates
bull bar, brush bars and steps
winch
UHF and aerial
air compressor
driving lights
roof platform
solar panels
DC-DC charger
fridge and fridge slide
12V oven
camp lighting
aftermarket head unit, speakers and amplifiers
canopy
towing mirrors
awning
At the time, those accessories alone added up to more than $22,000. Pretty comprehensive, right? Not quite.
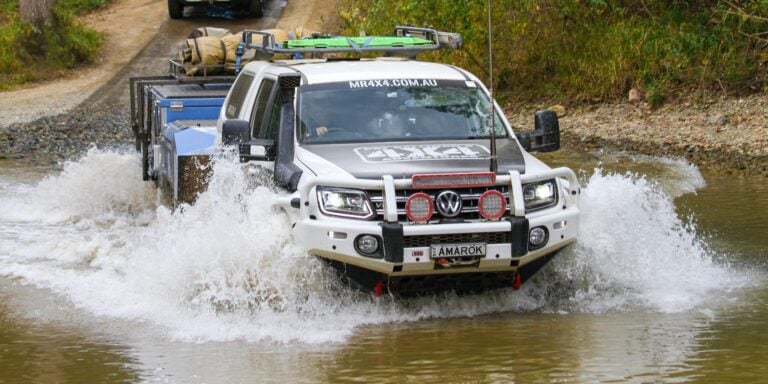
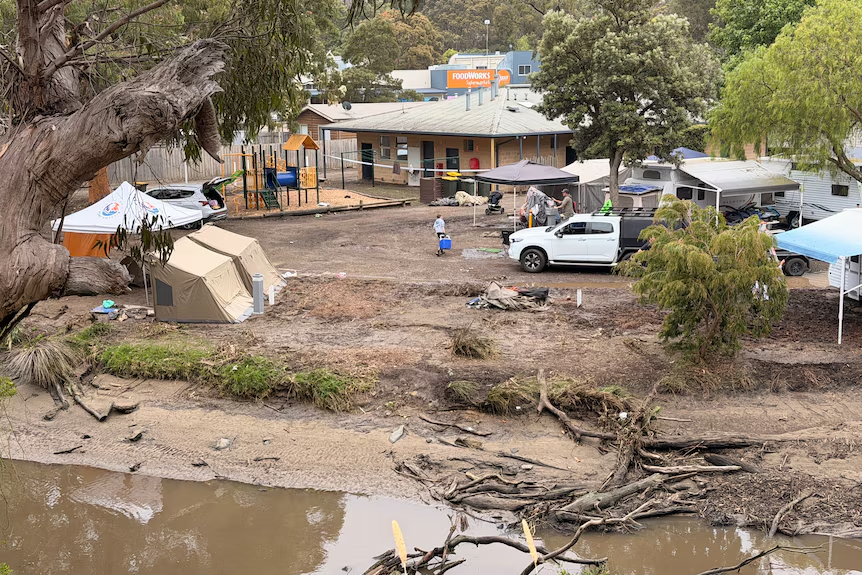
Are you absolutely certain that you are covered in a place like this?
The modifications and accessories that are easy to forget
When someone else went over the HiLux, another substantial list of equipment emerged.
There was the tow bar. The aluminium tray. The actual roof racks supporting the roof platform. The auxiliary battery. The electrical fit-out. Under-tray toolboxes. The snorkel. Gauges. Tyre-pressure monitoring system. Secondary fuel filter. 12V sockets. Even the seat covers and floor mats.
At the prices recorded at the time, the forgotten items added another $7,635 to the build. The figures themselves are now dated, but that’s not really the point.
The lesson is that when you live with a vehicle every day, many modifications stop looking like modifications. That snorkel has been hanging off the guard for five years. The auxiliary battery disappeared behind a panel the day it was installed. The tow bar might have been fitted before you even bought the vehicle. But replacing all of it after a total loss could add up very quickly.
There’s another consideration too: installation. Depending on your insurer and policy, the cost of labour associated with modifications may also be relevant when determining how much cover you need. So rather than guessing what your 4WD is worth, spend some time actually working it out.
Walk around your 4WD before you check your insurance
One of the simplest ways to review your insurance is to grab your phone and physically walk around the vehicle. Start at the front and work backwards.
Bull bar? Winch? Driving lights? Bash plates? Suspension? Wheels and tyres? Snorkel? Roof rack? Awning? Canopy? Drawers? Fridge? Battery system? Solar? Tow bar? Then open the bonnet, doors, canopy and drawers and look at what you’ve installed inside.
Better yet, ask someone else familiar with 4WDs to look over the vehicle. A fresh set of eyes can spot things you’ve become so accustomed to seeing that you no longer think of them as aftermarket additions.
Keep receipts where possible and consider maintaining a simple spreadsheet or list of your modifications, when they were fitted and approximately what they would cost to replace. Then update it whenever the vehicle changes.
Are your modifications and accessories actually covered?
This is where you need to read your own policy rather than assume all comprehensive 4WD insurance works the same way. Ask your insurer how they treat modifications and accessories, whether you need to declare them individually, and whether any limits apply. For example, Club 4X4 offers specialist 4WD insurance that allows modifications and accessories to be insured separately from the base vehicle at an agreed value.
It’s also worth establishing the difference between something considered a modification or accessory and portable touring gear. A permanently fitted fridge slide, for example, may be treated differently from the portable fridge sitting on top of it. The same could apply to permanently fitted lighting compared with portable camp lights, or a fixed water tank compared with jerry cans.
Don’t assume that because something is normally carried in your 4WD, it’s automatically covered by your vehicle insurance.
More often than not, you’ll drive unnamed tracks that look like this…
Where are you actually covered?
For anyone who takes their 4WD beyond the blacktop, this is arguably just as important as the dollar value of the vehicle. Insurance policies differ, so check the Product Disclosure Statement (PDS) and ask your insurer directly about the places you actually drive.
That might include:
unsealed and unnamed tracks
beaches
water crossings
private property
4WD parks
remote-area travel
This is one area where specialist 4WD insurers can differ from general motor insurers. Club 4X4, for example, states that its comprehensive cover applies anywhere in Australia your 4WD is legally allowed to go, including beaches, bush tracks, water crossings and private property with permission.
Don’t rely on what a mate says their insurer covers or what you remember reading online several years ago. Policies and their terms can change.
If you’re planning a trip that involves significant off-road travel, ask specific questions. If you’re heading to a beach, ask about beach driving. If your trip includes water crossings, ask about water crossings. If you’re heading onto private property or into a 4WD park, ask about that too.
What about off-road recovery?
There’s another question worth asking before disappearing down a remote track: what happens if your 4WD is damaged or stranded somewhere a conventional tow truck can’t reach? Getting a vehicle out of a remote location can be considerably more complicated than having it towed from the side of a highway.
Check whether your policy includes off-road recovery, whether it’s optional, what limits apply and what process you need to follow when arranging a recovery. You don’t want the first time you investigate that part of your policy to be when your 4WD is sitting disabled hundreds of kilometres from home.
Some specialist policies also offer dedicated off-road recovery cover. Club 4X4, for example, offers Off-Road Recovery Cover designed for situations where a vehicle is stranded somewhere that’s not accessible by a conventional two-wheel-drive tow vehicle.
… to be able to find those little hidden away and stunning spots like this.
Can you reduce your insurance premium?
Once you’ve established the level of cover you need, it’s worth asking whether there are legitimate ways to reduce the premium without sacrificing cover that’s important to you.
One option may be choosing a higher excess in exchange for a lower premium. The trade-off, of course, is that you’ll need to contribute more if you make a claim where that excess applies. Insurers may also have different rating factors, discounts or policy options, so compare the overall cover rather than looking at the premium alone.
A cheaper policy isn’t necessarily worse, just as a more expensive policy isn’t automatically better. What matters is whether the policy suits the vehicle you’ve built and the way you actually use it.
Don’t set and forget your 4WD insurance
A 4WD build rarely stays finished for long. You add a new awning. Upgrade the suspension. Install a lithium battery. Replace the fridge. Fit a long-range fuel tank. Add a canopy or spend thousands on an electrical system.
Individually, those upgrades might not seem significant enough to make you think about insurance. Collectively, they can substantially change the value of your vehicle and its setup. So make reviewing your insurance part of your regular 4WD maintenance.
Check the insured value. Check your modifications and accessories. Check your portable gear. Check where you can drive and what happens if you need a remote recovery. And read the current PDS rather than assuming your cover hasn’t changed.
Hopefully, you’ll never need to find out how good your insurance really is. But if you do, that’s a much better time to discover you listed everything than to start remembering all the things you forgot.